Donating Real Property: Retained Life Estate vs. Charitable Remainder Trust
-Some planned giving programs will accept gifts of real property through a retained life estate or a charitable remainder trust. Determining which split-interest gift is the right option depends on the needs and interests of the donor and the charity. The two options are described below followed by some questions to help guide you through conversations with your donors about gifts of real property.
Early Termination of a Charitable Remainder Trust (CRT) and Early Termination Checklist
-When a donor funds a charitable remainder trust (CRT), the assets are irrevocably transferred to the trust. The trust makes distributions to one or more non-charitable beneficiaries, usually including the donor, for life and/or a term of years (not to exceed 20 years), after which the remainder passes to charity. The donor receives a charitable deduction at the time of the gift to the CRT, which is the present value of the remainder interest expected to pass to charity. The remainder interest is calculated based on the life expectancy of the beneficiaries, the term of years, or a combination of the two. For CRTs funded after July 28, 1997, the remainder value must be at least 10% of the initial gift value.
A CRT is irrevocable, however, the trust can be terminated early, with the remainder passing then to charity if all the parties (trustee, beneficiary, and charity) agree.
Why Is the CRT Charitable Deduction So Much Smaller Than the Projected Remainder?
-PG Calc’s PGM Anywhere gift illustration software offers the ability to run projections for charitable remainder trusts that provide an estimate of the long-term outcome of the gift arrangement. Based on a number of input assumptions, the gift planning professional can give the prospective donor a reasonable idea of what is possible over time. None of the future numbers are guaranteed, of course, but modeling can serve as a useful tool in framing the overall picture.
While the long-range estimates can be helpful for a donor – and for his or her advisors – the process sometimes results in a number of questions. One of the most consequential questions we hear regarding the trust projections in PGM Anywhere is why the charitable deduction is so much smaller than the projected remainder amount. We generally refer to the deduction as the estimated value of the gift to the charity, but that is also how we explain the projected remainder amount. In some cases, the two numbers can be worlds apart. If they represent essentially the same concept, how can we see two numbers so dramatically different? Let’s take a look at what is behind the numbers.
2025 Was Good and We’d Like More of the Same: A Summary Investment Review
-In the world of fiduciary investment portfolios, we’ve been on a fairly steady roll over the past few years. We saw economic collapse on a global scale in 2020 as a result of the worldwide pandemic, but somehow, at the end of the year, the major stock and bond indices produced positive returns. On the other hand, both the stock and bond indices produced disastrous results in 2022. It was one of the only years in recent history wherein both stocks and bonds sustained significant losses. And yet, investment performance the very next year was quite strong, and 2024 was another good year.
There were myriad reasons for investment values to drop in 2025 – major layoffs and job losses, rising inflation, implementation of fairly severe tariffs, economic uncertainty – to name the most obvious. There was also tremendous upheaval in the federal government – massive firings by the Department of Government Efficiency (DOGE), a major effort to combat illegal immigration, and a Congress more divided than ever before. But somehow, the values of traditional mainstream investments still managed to rise over the course of the year.
Here are some of the facts . . .
All Boats Were Lifted: 2024 Another Strong Year for Traditional Investments
-Last year at this time, we were talking about how well traditional investment portfolios had done in 2023. After a truly disastrous performance in 2022, the stock market came roaring back in 2023, and the bond side held its own. Long-term performance averages seemed reliable again, and investors regained their confidence. So how did traditional investment portfolios do in 2024? As it turns out, they did quite well. Roughly speaking, the investment performance for traditional investment portfolios in 2024 was a repeat of the robust performance in 2023. Let’s take a look at some of the details.
After 2023, Are We Back to Normal?
-A year ago, we published an article under the tongue-in-cheek title of “That’s Alright, It Was Only Money.” We wanted to update our understanding of historical performance results for traditional investment portfolios after the disastrous conclusion of the year 2022. We used the S&P 500 Index as the benchmark for stocks and Barclay’s Aggregate Bond Index as the benchmark for fixed income. In 2022, the former ended the year with a return of minus 13.01%, and the latter ended the year with a return of minus 19.44%. That meant our prototypical investment portfolio, invested 50% in stocks and 50% in bonds, saw a blended investment return of minus 16.23%. At the time, we pointed out that the aggregate performance for 2022 was actually worse than the aggregate performance for the Great Recession year 2008, which was “only” minus 15.88%.
And now, after another year in the books, but with quite different results in 2023, we ask the question, “Are we back to normal?” It’s probably a rhetorical question, and it begs a more specific question: “What is normal, anyway?” The S&P 500 return in 2023 was 24.23%, and the Barclays Aggregate Bond Index return was 5.53%, resulting in a blended return of 14.88%. It was a great year for investment portfolios holding traditional asset classes! The improved numbers should make everyone feel a little better off. Does it give us greater confidence to make the argument that over many years, a prudent investor strategy results in positive returns? Let’s take a look at the actual numbers.
PG Calc QCD Survey: Many Charities Report Closing CGAs Funded With a QCD
-
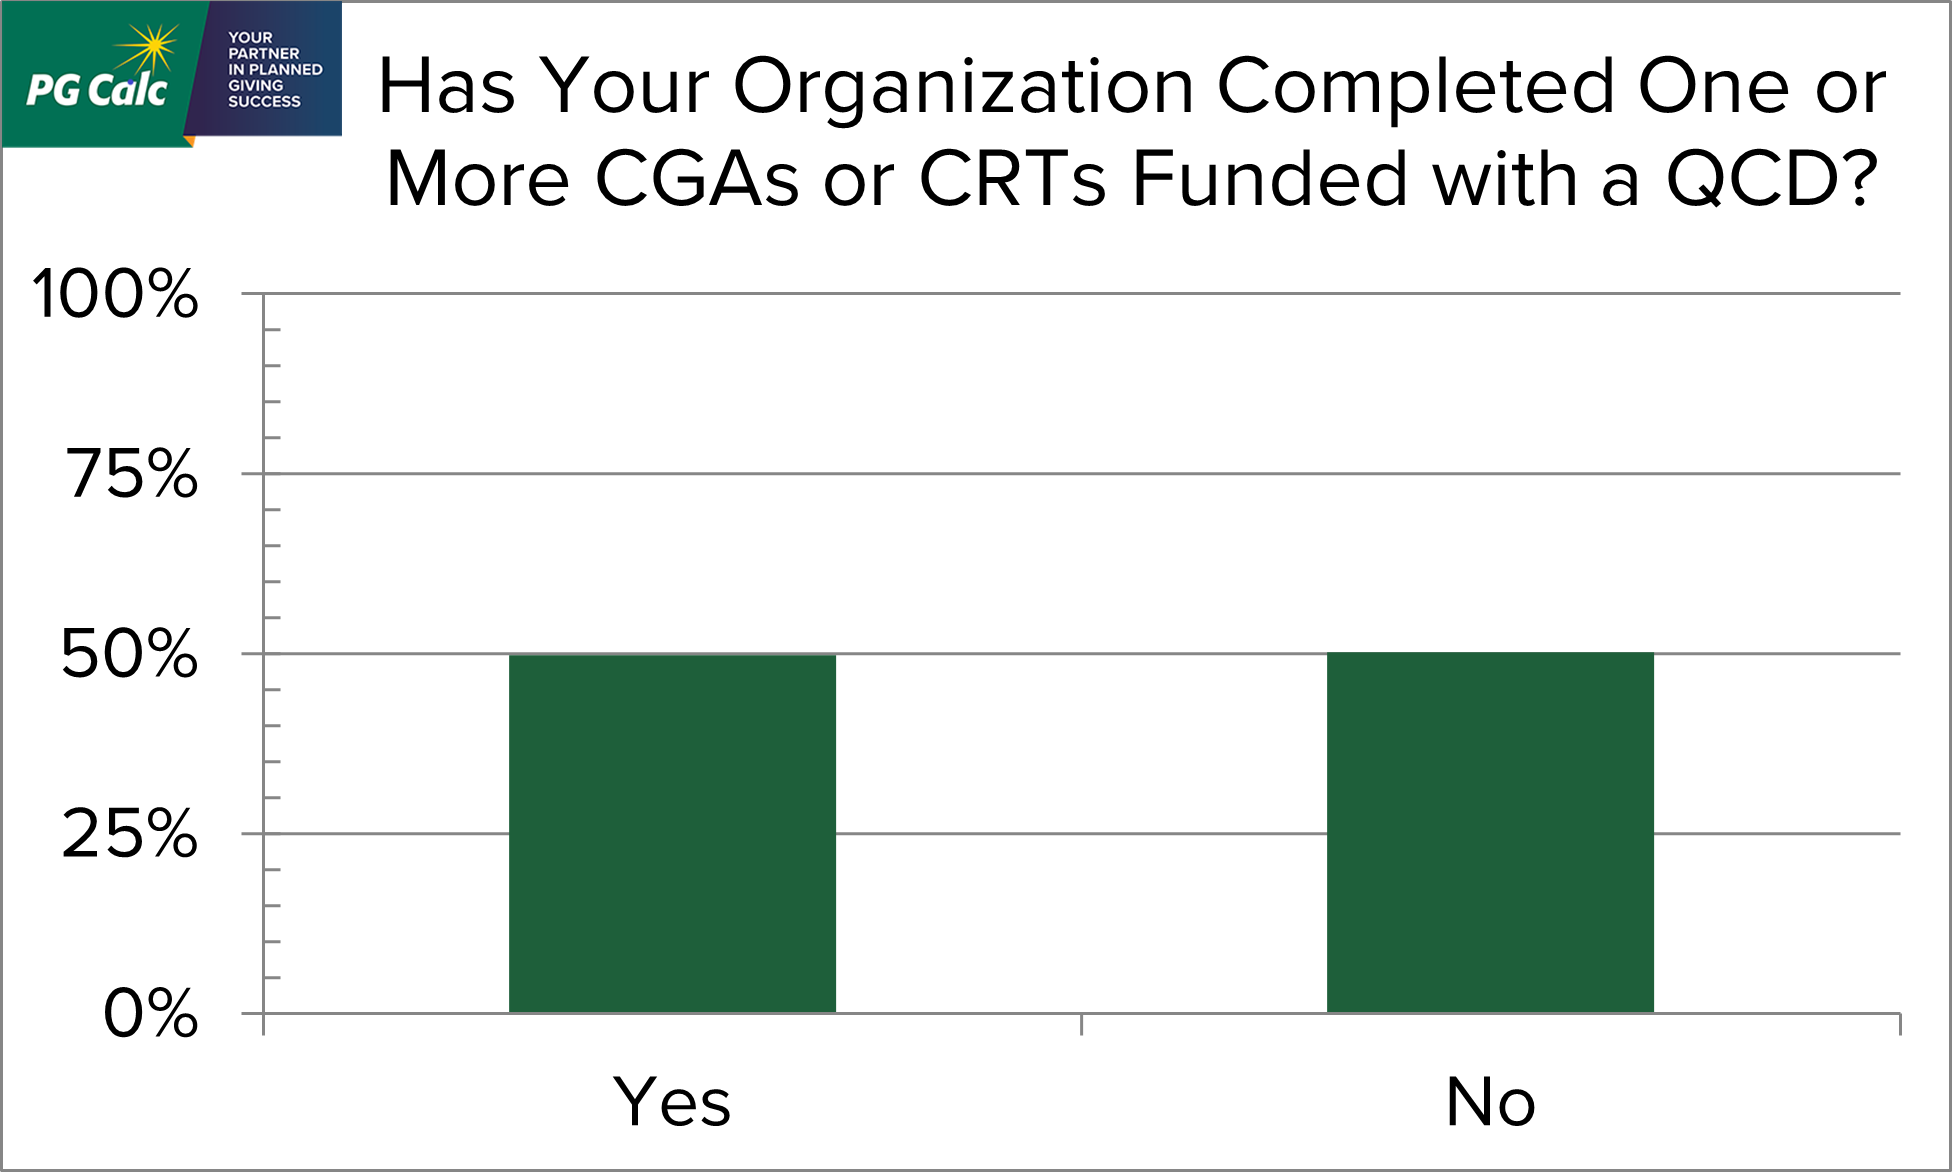 A new gift planning opportunity became available at the beginning of this year thanks to the Legacy IRA Act that passed late last December: funding a charitable gift annuity (CGA) or charitable remainder trust (CRT) with a qualified charitable distribution (QCD) from one’s IRA. Gift planners were rightfully excited to have a new gift plan to talk about with their donors. However, the new gift plan’s many requirements raised doubts about how popular it would be. Who would make these gifts? Now that we are most of the way through 2023, the QCD for life income plan’s place in planned gift fundraising has become clearer.
In their interactions with clients, our Client Services and Gift Administration teams have noticed a recent increase in the number of new CGAs funded with a QCD. This pattern piqued our interest. To investigate the popularity of this new gift option further, we sent out a survey to a broad fundraising audience. We summarize our results below.
That’s Alright – It Was Only Money (Putting 2022 in the Rearview Mirror)
-We’ve been saying for years that, when it comes to investments, charities should focus on the long-term picture. There are good years in the markets and bad years in the markets, but, with “prudent” investments, the long-term outcomes have been consistently positive. Whether it be the endowment assets of well-established organizations, or the investment portfolios of gift annuity programs and individual charitable remainder trusts, the general rule is to look at the bigger picture. But specific and dramatic swings in the investment markets – the stock market in particular – can have a chilling effect on donors with stock portfolios held over an extended period of time.
What do we say to the donors who have seen their investments lose significant value over the past 12 months or longer? And even within the organization, how do we respond to the more cautious voices among us who are spooked by double-digit declines in market values? We thought it would be helpful to take a look at the most recent investment performance measurements of mainstream investments.
Indexing the Qualified Charitable Distribution Amount
-The index adjustment uses the average Chained Consumer Price Index for All Urban Consumers (C-CPI-U) for each calendar year with 2022 as the base year. The average for a calendar year is taken from 9/1 of the previous year through 8/31 of the current year. Indexing starts with 2024, so the first adjustment will include 9/1/2021 - 8/31/2023. A fair estimate is that there will be an inflation adjustment of 10% to 15% for that period. If that is correct, the limit on outright QCDs would be between $110,000 to $115,000 and the limit on QCDs to a CGA would be between $55,000 to $58,000 (rounded $57,500 to nearest $1,000).
QCD to Life Income Gifts (the “Legacy IRA”) Frequently Asked Questions
-What is the “Legacy IRA”? Under certain circumstances, a donor can make a one-time tax-free Qualified Charitable Distribution (QCD) from their IRA in exchange for a life income gift. This is a once in a lifetime election, subject to the limitations explained below.